Obviously, every new company starts with a blank credit file. Lenders, suppliers, and landlords have no history to review, so early financing decisions often rest on the owner’s personal score. Learning how to build business credit gives your company a financial track record of its own, which can lead to better loan terms, higher credit limits, and less personal risk as the business grows. The steps below explain how to establish business credit from the ground up and how that history supports a future loan application.
TL;DR: Business credit is tied to your company’s EIN and built through a formal entity, a business bank account, a free D-U-N-S number, and vendor and card accounts that report on-time payments. Most new companies need several months of history before a score appears, and a solid profile makes it easier to get approved for a loan.
How Does Business Credit Work?
In short, business credit is a record of how your company borrows money and pays its bills. Personal credit follows your Social Security number (SSN), while business credit is linked to your Employer Identification Number (EIN). The three major business bureaus are Dun & Bradstreet, Experian, and Equifax, and each uses its own scoring model. Dun & Bradstreet’s PAYDEX score runs from 1 to 100, and a score of 80 or higher indicates a company that pays on time or early.
The two profiles still overlap for most owners. Lenders and card issuers frequently ask newer businesses for a personal guarantee, so your personal credit score continues to matter in the first few years. That said, a strong business profile gradually lowers that reliance.
Steps To Establish Business Credit For A New Company
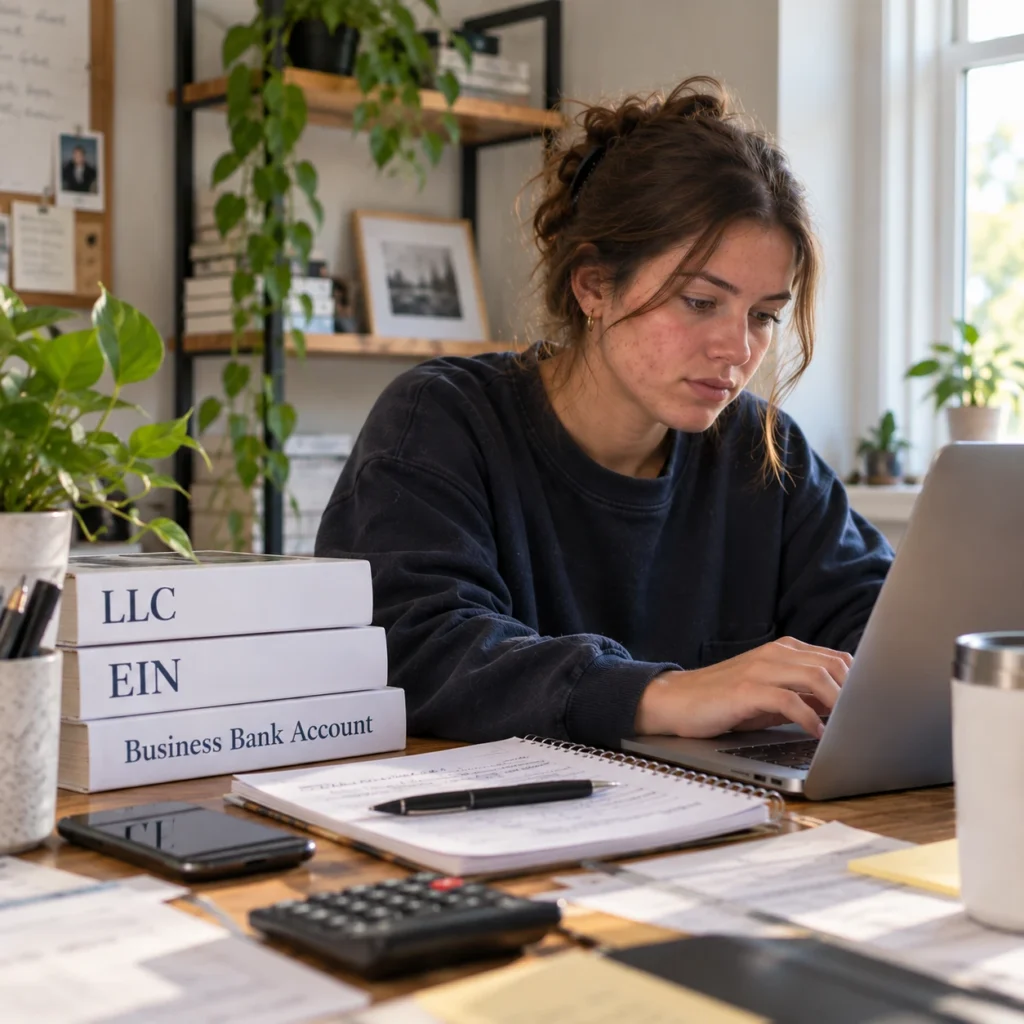
Formalize Your Business Structure
Registering as an LLC or corporation creates a legal entity that can hold credit in its own name. Sole proprietors can still build business credit, although the separation between owner and company is thinner. Entity choice also affects how the business is taxed, so it helps to weigh both questions together.
Get An EIN And Open A Business Bank Account
The IRS issues an EIN free of charge, and online applicants typically receive the number right away. Use it to open and operate a business bank account so revenue and expenses flow through the company. Clean separation also simplifies sorting business vs. personal expenses at tax time.
Register For A Free D-U-N-S Number
Dun & Bradstreet assigns D-U-N-S numbers at no cost. Free registration can take up to a month, and a paid option is available for faster processing. Once the number is active, suppliers can begin reporting your payment history to D&B.
Open Vendor Accounts That Report Payments
Trade credit from suppliers, often offered on net-30 terms, is one of the most accessible ways for a new company to start building history. Before opening an account, confirm that the vendor reports to at least one business bureau. Dun & Bradstreet needs at least three payment experiences from two or more reporting companies before it generates a PAYDEX score, and paying invoices ahead of the due date can lift that score above 80.
Add A Business Credit Card
A business credit card adds revolving credit to your file and makes expense tracking easier. Our guide on how to get a business credit card covers eligibility and the application process. Keep balances low and pay in full each month, since carrying high-interest lines of credit can strain cash flow quickly.
How Long Does It Take To Build Business Credit?
A PAYDEX score may appear within three to six months after a business receives its D-U-N-S number, depending on how quickly vendors report. Experian and Equifax follow their own timelines. Lenders generally look for a longer track record before approving larger amounts, so starting early gives your profile time to mature before you need financing.
How Business Credit Helps You Get Approved For A Loan
Business credit is one piece of a larger picture when a lender reviews your application. Underwriters also look at tax returns, bank statements, and financial statements such as a balance sheet and income statement. A solid credit profile paired with accurate books gives a lender confidence that the business can handle new debt. Cloud accounting software such as Xero makes it easier to produce current financial statements whenever a lender asks, and as a Xero Platinum Partner, our team helps owners set up and maintain their books on the platform. For a closer look at the application process, see our article on how hard it is to get a business loan. The U.S. Small Business Administration also offers guidance on separating personal and business finances.
How JBS Supports Owners Building Business Credit
JBS provides bookkeeping and tax services to small business owners, freelancers, and real estate investors, and organized financials are often what move a loan file forward. Our bookkeeping and controllership team keeps your books lender-ready, while the business tax services team makes sure the returns a lender requests are accurate and filed on time. To see where your business stands today, start with a free financial assessment.
Note: This article is for educational purposes only and does not constitute tax advice. Tax rules, figures, and percentages are subject to change and this article may not be fully up to date; visit IRS.gov for the most current information and consult a tax professional for guidance specific to your situation.