Depreciation gives rental property owners and business owners a valuable deduction for every year they own an asset. When that asset is sold, the IRS looks back at those deductions and taxes part of the gain through a rule called depreciation recapture. Learning how recapture works before you list a property or sell equipment can help you estimate your tax bill and plan the sale with fewer surprises.
TL;DR: Depreciation recapture taxes the portion of a sale gain that comes from depreciation claimed on rental property or business assets, at up to 25% for real estate and at ordinary income rates for equipment. Planning tools such as a 1031 exchange, a stepped-up basis for heirs, and careful sale timing can defer or reduce the tax owed.
What Is Depreciation Recapture?
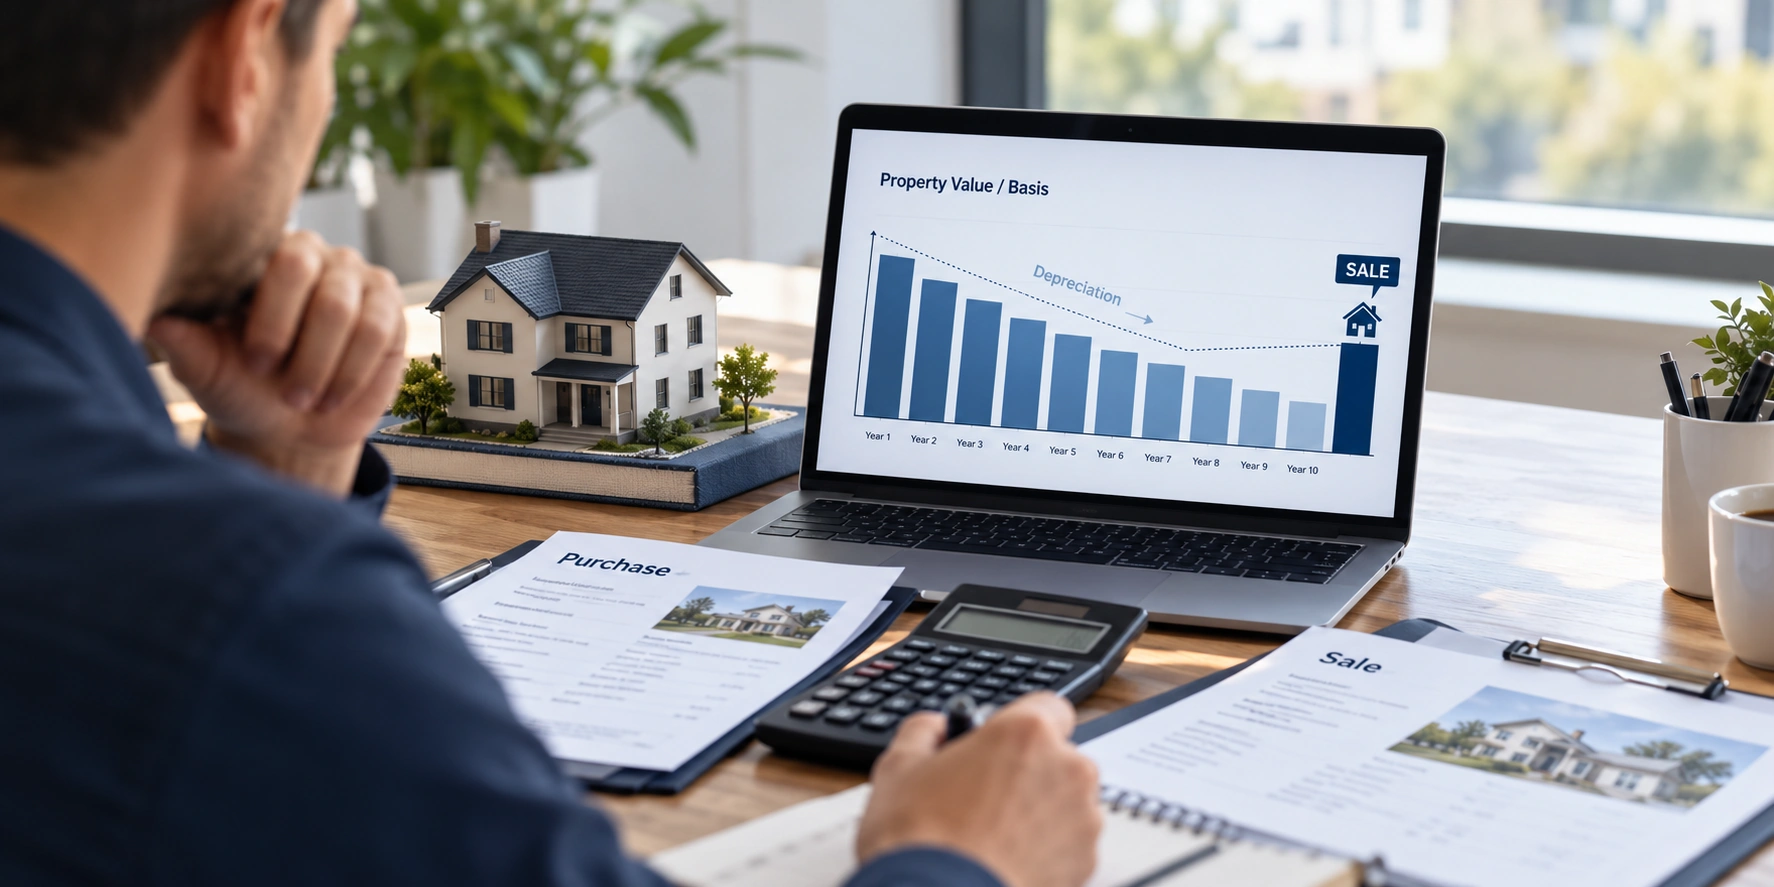
Depreciation recapture is the way the IRS taxes gain on a depreciable asset that results from deductions taken in earlier years. Each year you depreciate a rental building, a work vehicle, or a piece of equipment, your taxable income goes down. Those same deductions also lower your cost basis in the asset. When you sell for more than that reduced basis, a portion of the profit is taxed under separate rules from a standard capital gain.
How Depreciation Lowers Your Basis
Your adjusted basis generally starts with the purchase price, adds the cost of improvements, and subtracts depreciation. Residential rental buildings are depreciated over 27.5 years, commercial buildings over 39 years, and land is never depreciated. Many investors are surprised to learn that recapture is calculated using depreciation that was “allowed or allowable.” Skipping a deduction you were entitled to take still reduces your basis as if you had claimed it.
How Is Depreciation Recapture Taxed?
The tax treatment depends on the type of property sold. Sales of business and rental assets are reported on IRS Form 4797, and the IRS explains the full rules in Publication 544, Sales and Other Dispositions of Assets.
Section 1250 Recapture On Real Estate
Buildings used as rentals or in a business fall under Section 1250. The portion of your gain equal to prior straight-line depreciation is called unrecaptured Section 1250 gain, and it is taxed at your ordinary income rate up to a maximum of 25%. Any remaining gain is taxed at long-term capital gains rates of 0%, 15%, or 20% when the property was held for more than one year. Higher-income investors may also owe the 3.8% net investment income tax.
Section 1245 Recapture On Equipment And Personal Property
Machinery, vehicles, furniture, computers, and similar assets fall under Section 1245. Gain up to the total depreciation taken is taxed as ordinary income with no special cap. Business owners who used Section 179 expensing or bonus depreciation should pay close attention here, since writing off an asset in full during year one means most of the sale price may be recaptured later. Cost segregation studies on rental property can also reclassify parts of a building as Section 1245 property, which raises recapture exposure on those components.
An Example Of Depreciation Recapture On A Rental Property
An investor buys a rental home for $325,000, with $50,000 allocated to land and $275,000 to the building. Annual depreciation comes to $10,000, so after ten years the investor has claimed $100,000 and the adjusted basis sits at $225,000.
If the property sells for $425,000, the total gain is $200,000. The first $100,000 is unrecaptured Section 1250 gain taxed at up to 25%, and the remaining $100,000 is taxed at long-term capital gains rates. Selling costs and improvements are left out of this example for simplicity, and both would change the final figures. Our team runs projections like this for clients well before closing.
Ways To Reduce Or Defer Depreciation Recapture
Several planning options can lower or delay recapture when they are set up correctly.
1031 Like-Kind Exchanges
A 1031 exchange allows investors to sell one investment property and purchase another like-kind property while deferring both capital gains tax and depreciation recapture. Strict deadlines apply, including 45 days to identify a replacement property and 180 days to close. The IRS outlines eligibility on its like-kind exchanges page.
Stepped-Up Basis For Inherited Property
When an owner passes away, heirs generally receive the property with a basis stepped up to its fair market value on the date of death. That step-up eliminates the recapture that would have applied during the original owner’s lifetime. Our article on taxes on an inheritance covers how this works for beneficiaries.
Timing The Sale
Selling in a lower-income year can keep more of the gain in lower brackets. An installment sale can spread capital gain across several years, although recapture on Section 1245 property is generally taxed in the year of sale. Investors expecting a large bill may want to review how to make estimated tax payments to avoid underpayment penalties.
How JBS Helps Real Estate Investors Plan For Recapture
JBS provides tax services to real estate investors, from tracking depreciation on Schedule E each year to modeling the tax impact of a future sale. Our team reviews depreciation schedules, basis records, and exit options so clients know what to expect before signing a purchase agreement. JBS provides tax services to small business owners as well, including planning around equipment sales and Section 179 deductions through our business tax services.
Accurate recapture calculations depend on clean asset records. As a Xero Platinum Partner, our bookkeeping and controllership team uses Xero’s fixed asset tools to log purchase dates, costs, and accumulated depreciation for each asset, so the numbers are ready when it’s time to sell. To talk through your situation, book an appointment with our team.
Note: This article is for educational purposes only and does not constitute tax advice. Tax rules, figures, and percentages are subject to change and this article may not be fully up to date; visit IRS.gov for the most current information and consult a tax professional for guidance specific to your situation.